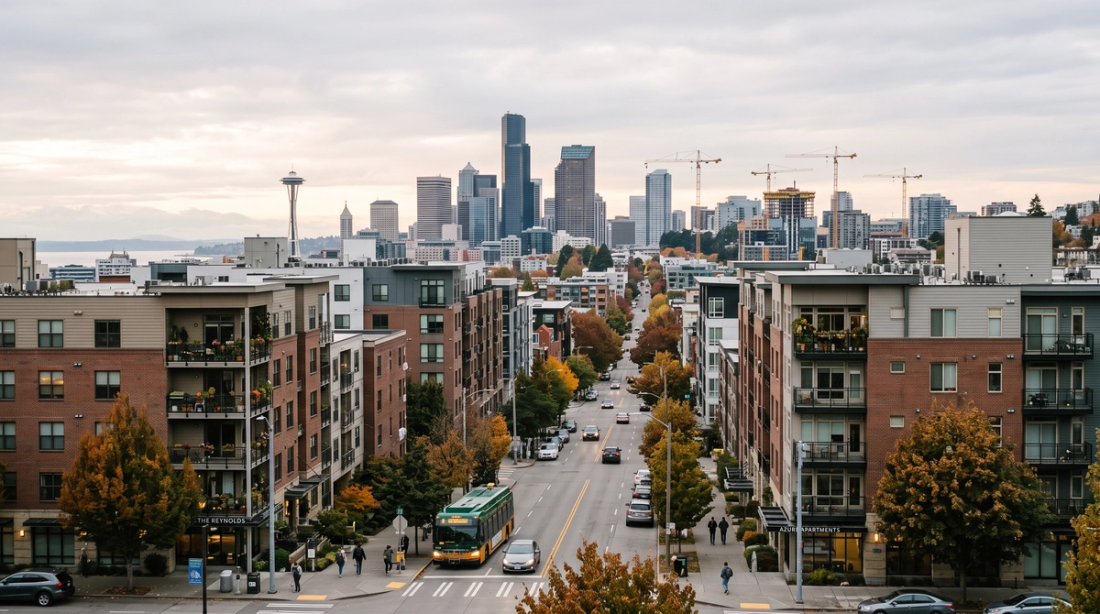
Seattle Apartment Vacancy Falls as New Deliveries Slow
Seattle apartment vacancy fell to 6.6% in the third quarter as occupied-unit growth outpaced completions. Asking rents rose annually but slipped from the second quarter.
Rising occupancy, constrained development, and improving operating results are strengthening the outlook for senior housing—but also heightening pressure on existing operators.
So what: With few new communities underway, operators with strong occupancy, disciplined pricing, and reliable care delivery may be better positioned to capture rising demand.
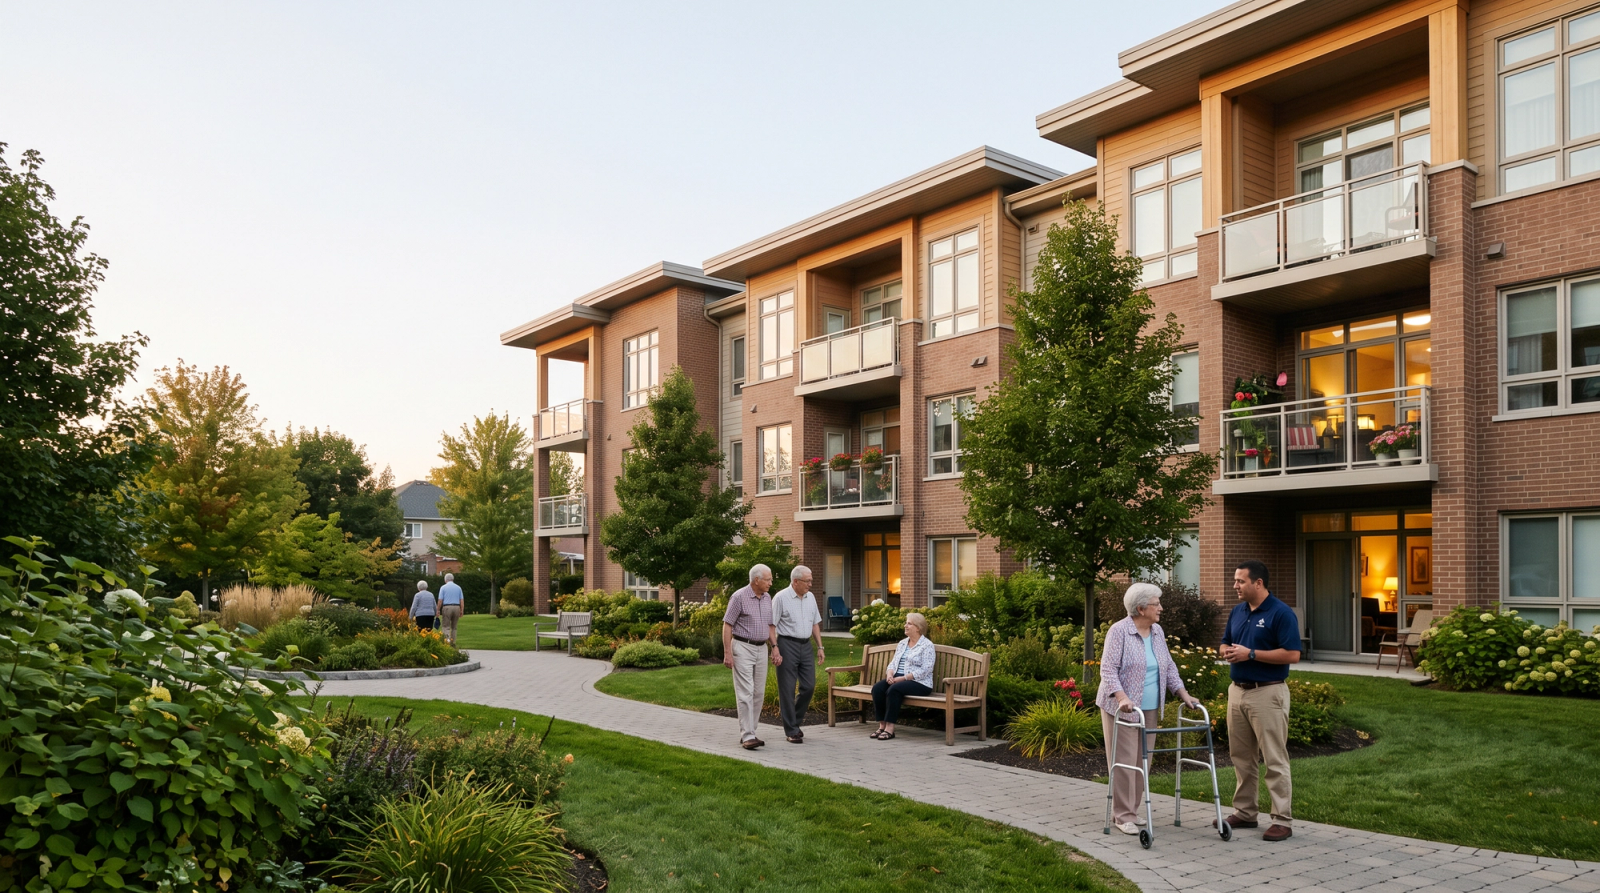
WASHINGTON, D.C. — Demand for senior housing has outpaced new supply by more than three to one during the past four years, creating a favorable operating and investment outlook even as elevated interest rates continue to limit new development, according to data presented by the National Investment Center for Seniors Housing & Care.
Across 140 NIC primary and secondary markets, 85 have no senior-housing projects under construction, while another 26 have only one project underway, according to the analysis reported by Senior Housing News. New projects that begin today take an average of 29 months to reach completion, limiting the likelihood of a near-term supply response.
The imbalance is showing up in property performance. In 31 primary markets, 61% of senior-living properties are operating above 90% occupancy, while another 16% are between 85% and 90%, NIC data showed. Senior housing has led major commercial-property sectors in year-over-year occupancy growth for four consecutive years, NIC Senior Principal Omar Zahraoui said during a recent webinar.
The conditions are supporting rent growth and improving net operating income, although performance remains uneven across operators and markets. Median operating margins have improved from pandemic-era lows but still vary widely, with higher-performing properties separating themselves from less stable operators.
For investors, the story is increasingly an acquisition and recapitalization opportunity rather than a ground-up construction cycle. Higher financing costs and long delivery timelines have made new projects harder to justify, while existing communities can benefit from tightened supply and growing demand from older adults.
That dynamic is already influencing capital allocation. National Healthcare Properties, for example, recently agreed to sell 40 outpatient medical facilities for approximately $531 million as part of a strategy to become a pure-play senior-housing owner. The company expects to use approximately $511 million in proceeds, after retiring portfolio debt, to repay its revolver and acquire senior-housing properties. It has also identified roughly $244 million in senior-housing acquisitions involving 724 primarily assisted-living and memory-care units, according to Bisnow.
For property operators, the tightening market does not eliminate execution risk. Higher occupancy can expose staffing gaps, move-in bottlenecks, maintenance backlogs, and challenges in delivering consistent care and resident experience. The operators most likely to benefit from limited supply will be those able to convert demand into stable occupancy, protect margins without overreaching on rates, and maintain service quality as census rises.
The supply shortage also gives existing operators and owners more influence in their local markets, but it raises an affordability concern for residents and families if rate growth outpaces household resources. In the near term, however, the mismatch between supply and demand is expected to keep senior housing firmly in focus for operators, lenders, and investors.
Seattle apartment vacancy fell to 6.6% in the third quarter as occupied-unit growth outpaced completions. Asking rents rose annually but slipped from the second quarter.
Residents remember slow repairs at renewal time. Property managers need to measure maintenance service as a retention and revenue function, not just a closed-ticket count.
The highest signed rent is not always the best lease. Here’s how apartment operators can weigh vacancy, concessions, lease terms and renewals to protect net revenue.